Employee stock options are designed to attract, incentivise, and retain talent. That is how they are presented to the board and described in offer letters. But the moment a company enters an M&A transaction, an arrangement built by the HR function becomes a term the deal lawyers have to price, and it is very often the last term anyone looks at.
The problem is easiest to see through an example. A company is being acquired for INR 1,000 crore. A senior employee holds options representing 1% of the company on a fully diluted basis and reasonably expects INR 10 crore. Whether that expectation is met turns on how many options have vested, whether they have been exercised, what the exercise price is, whether the scheme accelerates vesting on a change of control, whether investors hold liquidation preferences, whether the buyer is acquiring the employee's shares or substituting its own awards, and how the exercise is taxed if it happens days before closing. Depending on the answers, the same 1% can be worth INR 10 crore, a fraction of it, or nothing at all.
At that point, the ESOP has stopped being an HR matter. It drives the fully diluted capitalisation, the purchase price, the transaction structure, the exit waterfall, the tax position, the closing mechanics and, frequently, the buyer's plan for retaining the management team it is paying for. For Indian companies, these commercial questions also sit inside a regulatory frame: the Companies Act, 2013; the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021 in the case of listed companies; India's foreign exchange regime where employees or securities cross a border; and the Income-tax Act, 1961 — replaced, for tax years beginning April 1, 2026, by the Income-tax Act, 2025.
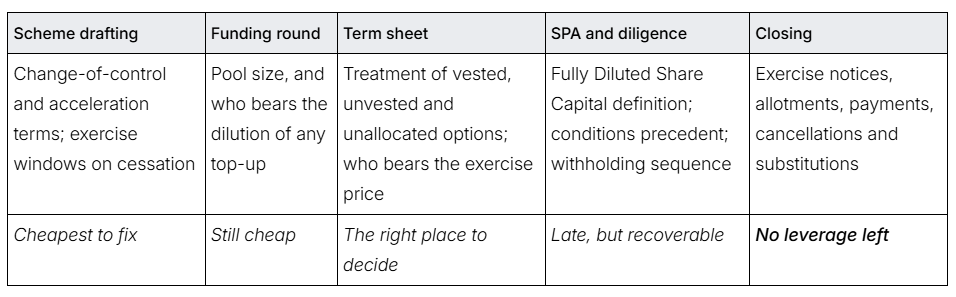
In our experience, almost every ESOP problem in an M&A transaction is a drafting problem created years earlier and discovered weeks before closing. This article sets out the issues that deserve attention and the stage at which each is best resolved.
The starting point in any acquisition involving ESOPs is reconciling the company's fully diluted capitalisation. Issued and paid-up capital rarely tells the whole story. The transaction team should identify:
Take a company where, on a fully diluted basis, founders hold 60%, investors 30%, granted employee options 7% and an unallocated pool 3%. The same company looks materially different depending on which basis is used:

This makes the definition of "Fully Diluted Share Capital" far more than a drafting formality. A difference in what sits in the denominator can materially alter the consideration payable to individual security holders, and we would treat it as one of the two or three most consequential definitions in the transaction documents.
a) Granted Options and Unallocated Pool
There is a further distinction that is easy to lose: options already granted to employees are not the same thing as an unallocated pool. Granted options are existing employee rights, subject to vesting and to the terms of the scheme. An unallocated pool is only capacity for future grants.
So if 8% of the fully diluted capital represents granted options and another 4% represents an unallocated pool, it does not follow that the whole 12% participates in the acquisition consideration. The transaction documents should address outstanding employee grants and the unallocated pool separately, and say what happens to each.
b) The ESOP Pool Can Also Be a Valuation Issue
This arises well before an exit, most often in PE and VC rounds. Suppose an incoming investor requires the company to maintain a 10% ESOP pool after its investment, while only 5% is available. The negotiation is rarely about whether the pool should be 10%. It is about who bears the dilution of the additional 5%. If the top-up sits in the pre-money capitalisation, the existing shareholders bear it; if it is created post-investment, the incoming investor shares it.
An ESOP pool provision in a term sheet is usually a valuation term rather than an employee incentive term, and founders should price it accordingly.
Outstanding options must then be split into vested and unvested, because the two require entirely different treatment. Assume an employee holds 20,000 vested options at an exercise price of INR 50 per share, and the buyer has agreed to an implied price of INR 500 per share. The obvious route is for the employee to exercise before closing and transfer the resulting shares to the buyer. But a vested option is not an issued share, and that route is not always available: depending on the scheme, the transaction structure and the tax analysis, the parties may instead use cancellation and settlement, substitution, rollover, or a combination of them.

Whichever mechanism is chosen, it should be settled while the transaction is being negotiated. Left to the fortnight before closing, exercise notices, board resolutions, allotments, withholding computations and employee communications all have to be completed at once.
Unvested Options
Unvested options are harder. Suppose a key employee holds 100,000 options and only 40,000 have vested when the acquisition happens. The remaining 60,000 may continue to vest on their original schedule, accelerate, be substituted with buyer awards, be replaced by a retention programme, or simply lapse. Which of those occurs is determined almost entirely by how the scheme and the grant letters were drafted, often years before anyone contemplated a sale.
That is the first lesson we would offer founders and investors: design the ESOP scheme with an exit in mind. A scheme that is silent on change of control does not become neutral. It hands the outcome to whoever has the most leverage at the time, and that is rarely the employee.
Whether unvested options should accelerate on a change of control is where the employee's interest and the buyer's interest diverge most sharply. The two standard structures pull in opposite directions:

Our own default, on either side of the table, is a double trigger with a clearly defined protection window and a tightly drafted "good reason" limb, because it pays the employee for the risk that actually materialises in a sale: losing the job. Blanket single-trigger acceleration is difficult to defend to a buyer; no acceleration at all is difficult to defend to the employees the buyer is relying on to stay.
The underlying tension does not disappear. The employee wants recognition for value already created; the buyer wants incentives tied to value yet to be created. Most acquisitions therefore land on a blend — some liquidity at closing, some equity rolled into the buyer, and some fresh retention incentive earned afterwards. Rather than letting a key executive monetise the whole value of their options at closing, part is realised immediately, and part is preserved through arrangements linked to the acquirer.
Drafting that blend needs care, and it is routinely rushed. An amount received for transferring a security and an amount received for agreeing to remain employed for three years are different things with different legal and tax characteristics. Labelling one as the other in the SPA does not change the analysis.
Option holders commonly equate their fully diluted percentage directly with the headline deal value. In practice, the headline number moves through four stages before any of it reaches an employee:
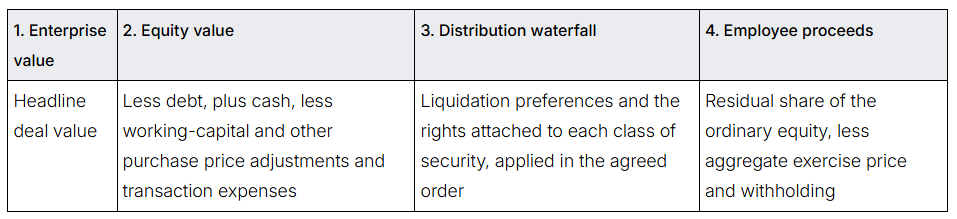
Those four are not interchangeable, and the distance between the first and the last is where employee expectations are usually lost.
a) The Liquidation Preference Problem
The arithmetic is worth doing. A company is sold for INR 250 crore. An institutional investor has invested INR 200 crore and holds contractual preferential rights on an exit, and an employee holds options over 1% on a fully diluted basis. The sale proceeds divide like this:
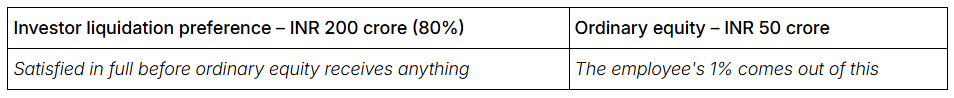
Multiplying 1% by INR 250 crore to arrive at INR 2.5 crore is wrong. The investor's preferential entitlement is satisfied before anything is available to ordinary equity, so the employee's 1% is a share of the residual INR 50 crore — around INR 0.5 crore. In a modest or distressed exit, where the sale price is not far above the amount invested by preferred investors, that residual can be close to nothing. The principle is worth stating plainly to employees, ideally long before an exit: percentage ownership tells them how much of the company they own, while the exit waterfall determines what that ownership actually pays.
An IPO or acquisition is not the only route to employee liquidity. Later-stage PE and VC rounds often combine a primary investment into the company with a secondary purchase from existing security holders. An INR 300 crore round might divide like this:

Subject to the structure and applicable law, part of that secondary component can be made available to eligible employees.
This matters most for employees who have spent five or seven years building a company and hold substantial paper wealth they have never been able to touch. A calibrated secondary rewards past value creation while keeping the employee invested in the upside still to come. The same logic applies where founders are permitted a secondary sale: allowing employees a proportionate share reinforces that ESOPs are genuine economic ownership rather than a number in an employment letter.
Tax is where ESOP treatment most often dictates the structure rather than following it, and it bites hardest when an acquisition produces an exercise followed immediately by a sale. Section 17(2)(vi) of the Income-tax Act, 1961 (Section 16(2) of the Income-tax Act, 2025) taxes the difference between the fair market value of the shares on the date of exercise, determined in the prescribed manner, and the amount recovered from the employee, as a perquisite in the employee's hands.
Take an exercise price of INR 100, a prescribed fair market value of INR 600 on exercise, and a sale at INR 1,000. One economic gain of INR 900 produces two separate taxing events:
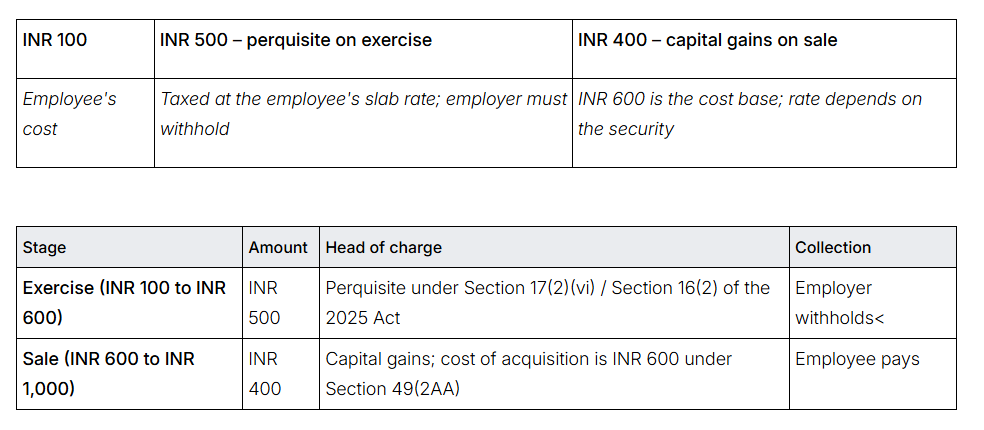
Which capital gains rate applies, and over what holding period, turns on the nature of the security, whether it is listed, and the employee's residential status.
a) The Liquidity-Tax Mismatch
The sharper problem arises when the exercise and the liquidity do not happen together. Exercise creates the perquisite charge and the employer's withholding obligation, even though the employee has sold nothing and received no cash. The employee faces tax today against liquidity at some uncertain point later. If the company never reaches an exit, the employee has paid tax on a gain never realised.
An acquisition that delivers exercise and liquidity simultaneously solves the commercial mismatch, but only if the mechanics are sequenced deliberately. Exercise, allotment, transfer, withholding computation and payment all have to line up, and in our experience the withholding step is the one most likely to hold up a closing.
The analysis gets harder as soon as employees or securities cross a border. Two situations recur, and they pull in opposite regulatory directions:

a) Indian Company With Non-Resident Employees
Where an Indian company has granted ESOPs to persons resident outside India, the treatment of those options in an acquisition has to be examined not only under the scheme and corporate law but also under India's foreign investment framework. Sectoral conditions, entry-route requirements and other foreign investment restrictions can all become relevant, depending on the company and the proposed transaction.
b) Indian Employees Holding Foreign Parent Options
The reverse situation is increasingly common in multinational groups and their Indian subsidiaries. Under the Overseas Investment framework, an investment by a resident individual through an ESOP or employee benefit scheme is categorised as Overseas Portfolio Investment where the prescribed conditions are met. RBI's Master Directions on Overseas Investment provide, among other things, that ESOP or employee-benefit holdings not exceeding 10% of the paid-up capital or stock of the foreign entity, and not resulting in control, may be categorised as OPI. They also make clear that where securities are swapped, each leg of the swap must independently comply with the applicable FEMA framework.
That last point matters where an overseas acquirer proposes to exchange target-company ESOPs for its own shares or options. What is commercially described as a simple rollover is, under FEMA, a swap requiring independent analysis of both legs. Test it early, because the answer can change the structure of the deal rather than merely the paperwork.
For a listed Indian company, the analysis goes well beyond Section 62(1)(b) of the Companies Act and Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014. Listed-company employee benefit schemes are governed by the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021, as last amended on December 4, 2025.
The regulations cover employee stock option schemes and other specified share-based employee benefit arrangements, and impose requirements on shareholder approval, administration through a compensation committee, variation of scheme terms, vesting, exercise and disclosure.
The practical consequence is that employee rights in a listed company cannot simply be amended, extinguished or replaced through the SPA. Whatever the parties agree commercially must be tested against the SEBI framework, the scheme documents, and the approvals the proposed action requires — and it is the approval timetable, not the negotiation, that sets the closing date.
For a company with a meaningful employee equity programme, ESOPs should not sit as one line item in the employment section of the diligence report. A focused exercise should reconcile four dimensions:

One category deserves particular attention: former employees. Someone who has left the company may still hold rights in respect of vested options through the applicable exercise period. The acquirer should identify former employees, vested options at cessation, exercise windows, exercises actually completed, options that have lapsed, and any discretionary extensions the company granted along the way. This is the most common source of error we encounter, and it is not a small one. If the formeremployee position is wrong, the fully diluted cap table used to price the acquisition is wrong.
Once the commercial treatment has been settled, it should be hardwired into the transaction documents. Depending on the structure, the SPA and related documents may need to address:
Five provisions in particular repay careful drafting.
Consider a clause that states only:
"The treatment of ESOPs shall be mutually agreed prior to Closing"
A clause of that kind postpones a potentially material issue to the precise moment at which the parties have the least time and the least leverage to resolve it. We would be reluctant to sign a deal with a material ESOP pool on that footing.
Before signing an M&A transaction involving a material ESOP pool, the transaction team should be able to answer these ten questions:
If any of those answers is unclear at signing, the ESOP workstream is not finished.
The same instrument means four different things to the four parties around the table:
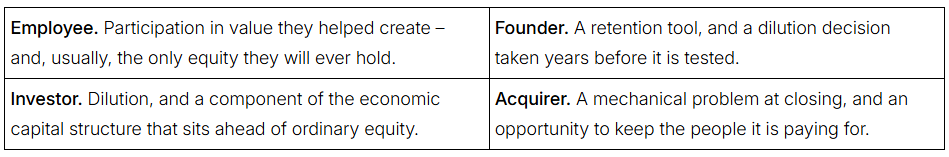
For the transaction lawyer, all four perspectives have to be reconciled within the same set of documents, and they cannot all be given what they want.
That is why the useful question is not what happens to the ESOP scheme after the acquisition, but a narrower one: what rights have already been created, who bears them economically, how they affect the purchase price and the exit waterfall, what becomes of vested and unvested options at closing, what the tax and regulatory consequences are, and how the interests of employees, existing shareholders and the acquirer are to be balanced.
An ESOP begins life as an employee incentive. At exit it becomes a deal term. The difference between the two is almost always a question of when someone looked at it, and the cost of looking late is usually paid by the employees who were told the options were worth something.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.